Personal Tax Return Filing in Canada: A Complete Walkthrough
From T1 slips to NetFile submission, here's how personal tax filing works for individuals, sole proprietors, and partnerships.
Filing a personal tax return (T1) in Canada is mandatory for most individuals — and for sole proprietors and partnerships, it's also where business income gets reported. Getting it right means claiming every deduction you're entitled to and avoiding the CRA's attention.
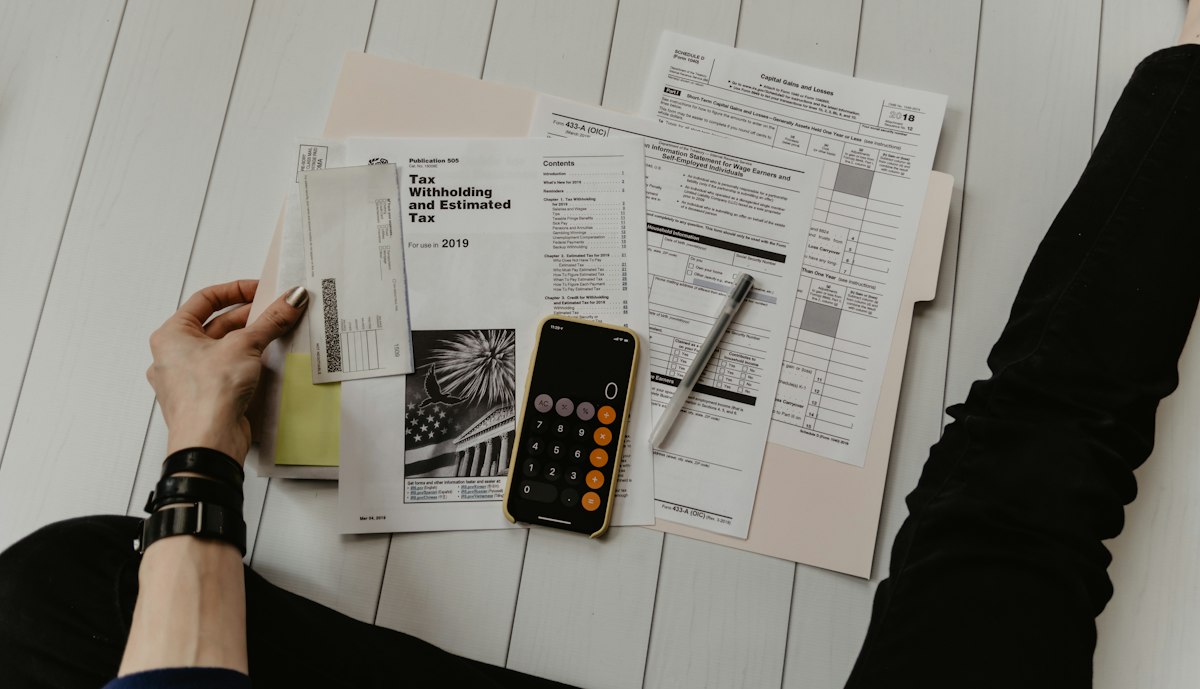
The T1 return pulls together your T4 (employment), T4A (pension/other), T5 (investment), and T3 (trust) slips, plus any self-employment income on Form T2125. Sole proprietors report business income and expenses here, so clean bookkeeping directly lowers your taxable income.
Capital gains and investment income add complexity. Disposing of stocks, rental property, or crypto triggers capital gains reporting, and the rules around inclusion rates and principal residence exemptions change often. Filing accurately and keeping clean records helps you stay organized and prepared.
Deadlines matter: the general personal filing deadline is April 30, but self-employed individuals (and their spouses) have until June 15 — though any tax owing is still due April 30. Miss the payment date and interest starts accruing immediately.
We prepare and file T1 returns for individuals, sole proprietors, and partnerships — ensuring every slip is captured, every eligible deduction is claimed, and the return is submitted electronically via NetFile for fastest processing and refunds.
Don't let a missed deduction or a late filing cost you. Book a free consultation and we'll review your situation, estimate your refund or balance owing, and file on time.
Ready to Balance Your Books?
Get a free consultation with True Balance Accounting. We'll review your books and outline clear next steps — no pressure, no judgment.
Book a Free Consultation